If you have ever wondered how auto financing works at a dealership, you are not alone. Many first-time buyers find the financing process confusing or intimidating. At Speck Motors, we believe every customer deserves a clear and honest explanation of how automotive financing works. Here is everything you need to know about getting a car loan at a dealership. What Is Auto Financing? Auto financing is the process of borrowing money to purchase a vehicle. Instead of paying the full purchase price upfront, you make monthly payments over a set loan term. Most auto loan terms range from 24 to 84 months depending on the lender and your situation. At the end of your loan term, you own the vehicle outright with no further payments required. How Does the Process Work? Step 1: Choose Your Vehicle The purchase price of your vehicle directly affects your monthly car loan payment. A lower purchase price means a smaller loan amount and a more manageable monthly payment. Our sales team will help you find the right vehicle across our new and used inventory. Step 2: Complete a Credit Application Our finance team will ask you to complete a credit application with basic personal and financial information. We then shop your application across multiple lenders simultaneously. That process is one of the biggest advantages of auto financing at a dealership versus a bank or credit union. Step 3: Our Finance Team Shops Your Application Our finance team submits your application to multiple lenders at the same time. Each lender reviews your application and responds with a loan offer. Our finance team presents you with the best available options for your specific situation. You select the offer that works best for your budget. Step 4: Review Your Loan Terms Before signing anything, our finance team reviews every detail of your auto loan with you. That includes the purchase price, interest rate, loan term, monthly payment, and total cost. There are no surprises and no hidden fees at Speck Motors. Step 5: Sign and Drive Away Once you are comfortable with your car loan terms, you sign the paperwork and drive away. Our finance team handles all paperwork including title transfer and lender documentation. The entire automotive financing process at Speck Motors is designed to be fast and stress-free. Key Auto Financing Terms You Should Know Interest Rate (APR) The interest rate is the cost of borrowing money expressed as an annual percentage. A lower interest rate means less money paid in interest over the life of your car loan. Your credit score is the biggest factor in determining the rate you qualify for. Loan Term The loan term is the length of time you have to repay your auto loan. Longer terms mean lower monthly payments but more total interest paid over time. Shorter terms mean higher monthly payments but less total interest paid. Down Payment A down payment reduces the amount you need to finance and lowers your monthly car loan payment. Most lenders prefer a down payment of at least 10 to 20 percent of the purchase price. Trade-In Value Your trade-in value can be applied directly toward your new vehicle purchase just like a down payment. Washington State also offers a trade-in tax credit that reduces the taxable purchase price of your next vehicle. Credit Score A higher credit score typically means a lower interest rate and better loan terms on your auto loan. A lower credit score may result in a higher rate but auto financing may still be available through our lender network. What If I Have Bad Credit or No Credit? At Speck Motors, we work with buyers at every credit level every single day. Bad credit, no credit, and first-time buyers are all welcome at our dealership. We work with a wide network of lenders who specialize in non-traditional automotive financing situations. A larger down payment, proof of stable income, and a co-signer can all significantly improve your chances of auto loan approval. What Documents Do You Need? Bring the following when you visit Speck Motors: Valid government-issued photo ID Proof of income including recent pay stubs or bank statements Proof of residence including a utility bill or lease agreement Proof of active auto insurance Down payment in the form of cash, check, or trade-in vehicle Your Social Security Number or ITIN for the credit application Ready to Get Started? Ready to apply for auto financing at Speck Motors in Sunnyside? Here is how to get started: Online: Visit our website and use our pre-qualification tool By Phone: Call our finance team directly to discuss your situation Walk-In: Stop by during business hours and our team will be ready to help Whether you are financing your first vehicle or your fifth, our team at Speck Motors is committed to finding you the best possible car loan for your budget. Come see us today. Apply for Financing
How to Improve Your Credit Score Before Buying a Car
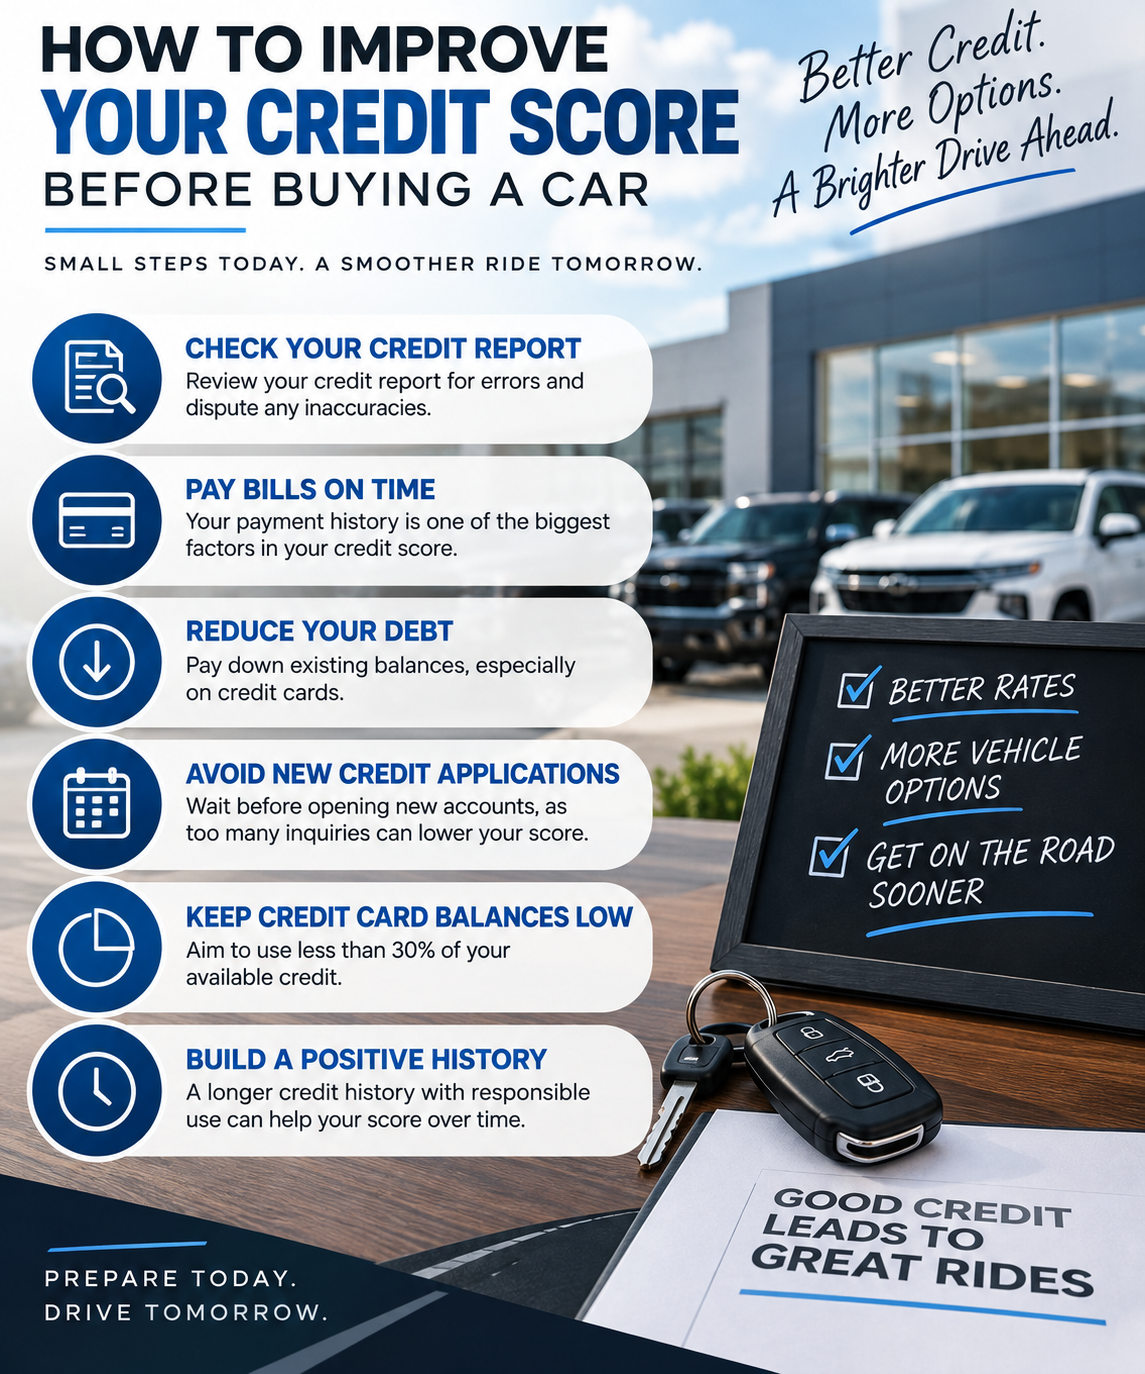
If you are planning to buy a car soon, your credit score is one of the most important numbers to know. A higher credit score means better automotive financing options, lower interest rates, and more affordable monthly payments on your car loan. The good news is that there are several proven steps you can take to build credit and improve your score before visiting Speck Motors in Sunnyside. Why Your Credit Score Matters for a Car Loan Your credit score is the single biggest factor lenders use to determine your car loan interest rate. A higher score means a lower interest rate and more savings over the life of your automotive financing agreement. Even a small improvement in your credit score can translate into significant savings on your monthly payment. Here is a simple example. A buyer with a 720 credit score may qualify for a 5 percent interest rate on a car loan. A buyer with a 580 score may receive a 12 percent rate on the same loan. That difference can add up to thousands of dollars over the life of your automotive financing agreement. How Is Your Credit Score Calculated? Understanding how your credit score is calculated helps you focus on the areas that matter most. Here is a breakdown of the key factors that determine your score: Payment history accounts for approximately 35 percent of your credit score Credit utilization accounts for approximately 30 percent of your score Length of credit history accounts for approximately 15 percent of your score Credit mix accounts for approximately 10 percent of your score New credit inquiries account for approximately 10 percent of your score Steps to Improve Your Credit Score Before Buying a Car Pay Every Bill on Time Payment history is the single most important factor in your credit score calculation. Even one missed or late payment can significantly damage your score. Set up automatic payments or calendar reminders to make sure every bill is paid on time every single month. Consistent on-time payments are the fastest and most reliable way to build credit over time. Pay Down Existing Debt Your credit utilization ratio is the second most important factor in your credit score. Credit utilization is the percentage of your available credit that you are currently using. Try to keep your credit utilization below 30 percent on every credit card and line of credit you have. Paying down existing balances before applying for a car loan can quickly and meaningfully improve your credit score. Do Not Open New Credit Accounts Opening new credit accounts generates hard inquiries on your credit score. Each hard inquiry can temporarily lower your score by a few points. Avoid opening new credit cards, personal loans, or other lines of credit in the months before applying for automotive financing. New accounts also lower the average age of your credit history which can further reduce your score temporarily. Check Your Credit Report for Errors Many people have errors on their credit report that are negatively affecting their credit score without their knowledge. You are entitled to one free credit report per year from each of the three major credit bureaus at annualcreditreport.com. Review your report carefully for any inaccurate information including incorrect balances, accounts that do not belong to you, and late payments that were actually made on time. Disputing and correcting errors can quickly improve your credit score without any additional financial effort. Become an Authorized User If you have a trusted family member or friend with good credit, ask them to add you as an authorized user on one of their credit cards. Being added as an authorized user can help you build credit by adding positive payment history to your credit score. You do not even need to use the card to benefit from the positive account history. This is one of the fastest ways to build credit for buyers with thin or no credit history. Keep Old Credit Accounts Open The length of your credit history accounts for approximately 15 percent of your credit score. Closing old credit card accounts shortens your average credit history and can lower your score. Keep your oldest credit accounts open and in good standing even if you do not use them regularly. A longer credit history demonstrates financial stability and reliability to lenders evaluating your car loan application. Consider a Secured Credit Card If you have little to no credit history, a secured credit card is one of the best tools available to build credit from scratch. A secured credit card requires a cash deposit that serves as your credit limit. Use the card for small purchases and pay the balance in full every single month. Over time, responsible use of a secured credit card will help you build credit and improve your credit score significantly. How Long Does It Take to Improve Your Credit Score? The timeline for improving your credit score depends on your current situation and the steps you take. Here is a general guide for Yakima Valley and Tri-Cities buyers: Correcting errors on your credit report can improve your score within 30 to 60 days Paying down credit card balances can improve your score within one to two billing cycles Building a consistent payment history takes six to twelve months to show meaningful improvement Recovering from a serious negative event like a bankruptcy or repossession can take two to five years What Credit Score Do You Need for a Car Loan? There is no single minimum credit score required to get a car loan. Every lender has different approval criteria and different risk tolerances. Generally speaking, a credit score above 660 will qualify you for competitive automotive financing rates at most lenders. A score between 580 and 659 is considered fair and may still qualify for auto financing at a higher interest rate. At Speck Motors, we work with buyers at every credit score level and will always do our best to find the right car loan for your situation. We Can Help You Get Approved Today Do not let a lower credit score stop you from getting into a quality vehicle at Speck Motors. Our finance team works with a wide network of lenders who specialize in all automotive financing situations. We have helped hundreds of Yakima Valley and Tri-Cities buyers get approved for a car loan regardless of their credit score. A larger down payment, proof of stable income, and a co-signer can all help improve your chances of approval today. Ready to Apply for Auto Financing at Speck Motors? Ready to take the next step toward your car loan at Speck Motors in Sunnyside? Here is how to get started: Online: Visit our website and use our pre-qualification tool to explore your options By Phone: Call our finance team directly to discuss your credit score and situation Walk-In: Stop by during business hours and our finance team will be ready to help Whether your credit score is excellent or needs some work, our team at Speck Motors is committed to finding you the best possible automotive financing solution for your situation. Come see us today and let us help you get into the right vehicle at the right payment. Apply for Financing